UK Invoice Requirements: What HMRC Requires on Every Invoice (2026)
Tax & Compliance Series
This guide is part of a comprehensive series. Explore all 202 topics:
What Must Appear on a UK VAT Invoice?
HMRC specifies exactly what information must appear on a full VAT invoice. Missing any of these fields can mean your customer cannot reclaim VAT — and you could face penalties during an HMRC inspection.
HMRC specifies exactly what information must appear on a full VAT invoice. Missing any of these fields can mean your customer cannot reclaim VAT — and you could face penalties during an HMRC inspection.
Full VAT Invoice (Over £250)
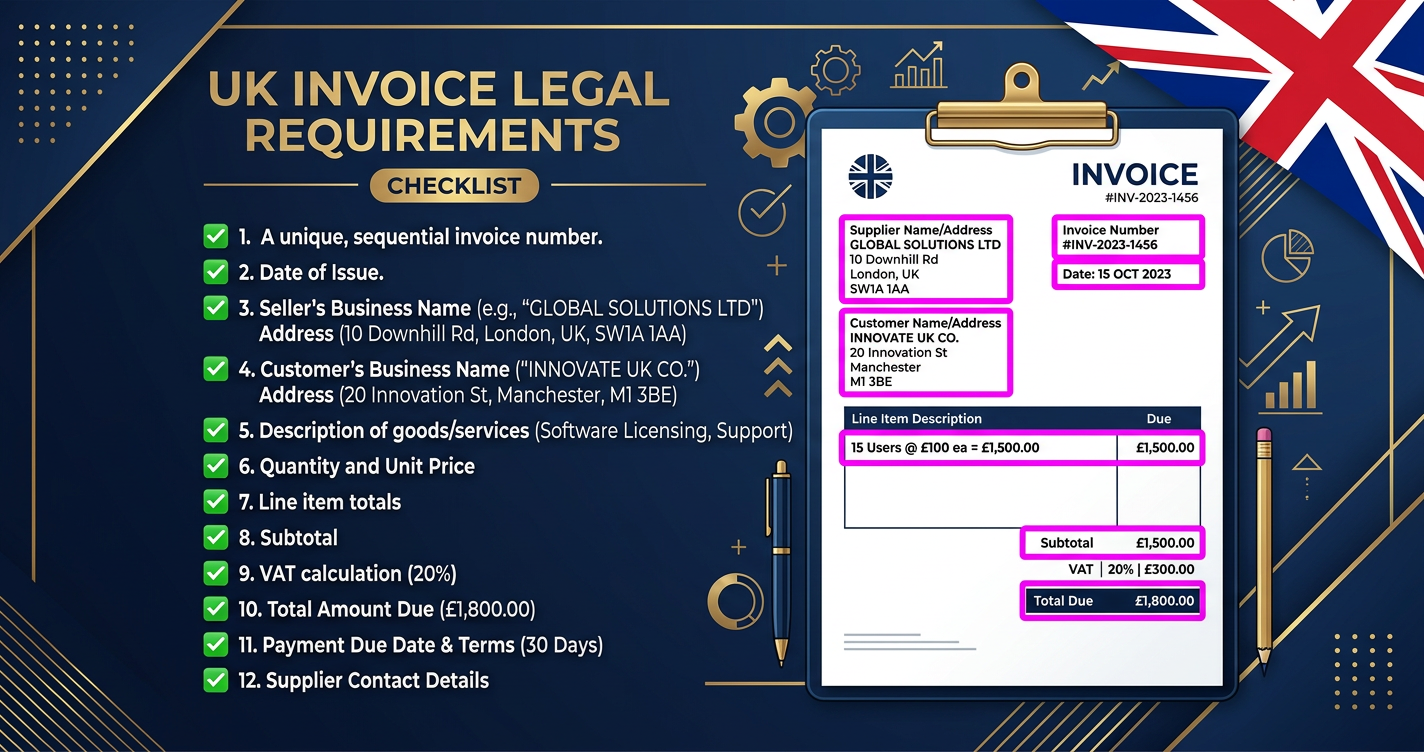
Every full VAT invoice must include:
- The word "Invoice" — clearly identified as an invoice
- Unique sequential number — no gaps in the sequence
- Date of issue
- Tax point (date of supply) — when goods were delivered or services performed
- Your business name and address
- Your VAT registration number
- Customer's name and address
- Description of goods or services — sufficient detail to identify what was supplied
- Quantity of goods or extent of services
- Unit price excluding VAT
- Rate of any cash discount
- Total amount excluding VAT
- Total VAT amount
- VAT rate for each item
- Total including VAT
Simplified VAT Invoice (Under £250)
For supplies under £250 (including VAT), you can issue a simplified invoice with:
- Your name and address
- Your VAT registration number
- Date of supply
- Description of goods or services
- Total amount including VAT
- The VAT rate charged
Note: you cannot issue simplified invoices to other VAT-registered businesses who need to reclaim input VAT — they'll need a full VAT invoice.
Modified VAT Invoice (Over £250 to Retail)
Retailers making supplies over £250 can issue modified invoices showing VAT-inclusive prices per item instead of the unit price excluding VAT.
Special Scenarios
Reverse Charge Invoices (CIS)
Construction industry subcontractors within scope of the domestic reverse charge must:
- Not charge VAT on applicable supplies
- Include the statement: "Reverse charge: VAT Act 1994 Section 55A applies"
- Show the amount of VAT that would have been charged
Zero-Rated and Exempt Supplies
If you supply zero-rated items (children's clothing, most food, books), your invoice must still show the 0% VAT rate. For exempt supplies, no VAT should be shown at all.
Invoicing in Foreign Currency
If you invoice in a currency other than GBP, you must also show the VAT amount in sterling, using HMRC's approved exchange rate for the date of supply.
Common HMRC Invoice Mistakes
Common HMRC Invoice Mistakes includes: Missing VAT number — your customer cannot reclaim VAT without it Gaps in invoice numbering — HMRC may query missing numbers during an inspection
- Missing VAT number — your customer cannot reclaim VAT without it
- Gaps in invoice numbering — HMRC may query missing numbers during an inspection
- Wrong tax point — the tax point determines which VAT period the transaction falls into
- Incorrect VAT rate — applying 20% to a zero-rated supply triggers penalties
- No customer details — full VAT invoices must include the customer's name and address
- Your business name, address and VAT number (never changes between invoices)
- An auto-incrementing invoice number field, so you never create a duplicate or a gap
- A tax point field separate from the issue date, since they are not always the same day
- A VAT rate column per line item, since some invoices mix standard, reduced and zero-rated items
Full vs. Simplified vs. Modified Invoices
Which invoice type you issue depends on the value of the supply and whether your customer needs to reclaim VAT. Here is how the three formats compare.
| Invoice type | When to use | Best for | Key limitation |
|---|---|---|---|
| Full VAT invoice | Any B2B supply, especially over £250 | Customers who need to reclaim input VAT | Requires the most fields — get one wrong and reclaim can be refused |
| Simplified VAT invoice | Retail-style supplies under £250 including VAT | Small consumer-facing transactions | Cannot be used for VAT-registered customers needing to reclaim VAT |
| Modified VAT invoice | Retail supplies over £250 to the general public | Retailers issuing itemised receipts | Shows VAT-inclusive prices per line, so it still needs care when totalling VAT |
How to Build a Compliant Invoice Template
The safest approach is to start from a template that already contains every mandatory HMRC field, then adapt the description and line items per job.
The safest approach is to start from a template that already contains every mandatory HMRC field, then adapt the description and line items per job. A reusable template should have fixed placeholders for:
Example of a compliant invoice header in plain text:
Invoice #INV-2026-0143
Issue date: 14 March 2026 | Tax point: 10 March 2026
From: Bright Studio Ltd, 12 Market Street, Leeds LS1 1AA — VAT No. GB123456789
To: Acme Retail Ltd, 8 High Street, Manchester M1 2AB
Record-Keeping Requirements Alongside Invoices
HMRC requires businesses to keep copies of all invoices issued and received for at least 6 years, in a format that can be produced on request during an inspection.
HMRC requires businesses to keep copies of all invoices issued and received for at least 6 years, in a format that can be produced on request during an inspection. Digital storage is acceptable and, under MTD, encouraged — as long as the records remain accessible and unaltered.
Frequently Asked Questions
What is the minimum a UK invoice must show to be VAT-compliant?
A full VAT invoice must show a unique sequential number, issue date, tax point, your name/address/VAT number, the customer's name and address, a description of the supply, quantities, unit prices excluding VAT, the VAT rate and amount for each item, and the total including VAT.
Can I issue a simplified invoice to any customer?
Only for supplies under £250 including VAT, and only when the customer does not need to reclaim input VAT as a VAT-registered business. If your customer needs to reclaim VAT, issue a full VAT invoice regardless of the amount.
Do zero-rated or exempt invoices need to show VAT?
Zero-rated supplies must still show a 0% VAT rate on the invoice. Exempt supplies should not show any VAT at all, and it is good practice to note that the supply is VAT-exempt.
What is a tax point and why does it matter?
The tax point is the date goods were delivered or services performed. It determines which VAT period the transaction belongs to, so getting it wrong can misstate a VAT return even if the invoice date is correct.
Is it legal to invoice UK clients in a foreign currency?
Yes, but you must also show the VAT amount in GBP on the invoice, converted using HMRC's published exchange rate for the date of supply.
Create HMRC-Compliant Invoices
Invoicemonk's invoice generator includes all mandatory UK fields, automatic 20% VAT calculation, and professional formatting that meets HMRC standards.
Invoicemonk's invoice generator includes all mandatory UK fields, automatic 20% VAT calculation, and professional formatting that meets HMRC standards. Get started →
More in this series (202 articles)
From this series
Stay audit-ready and compliant with tax regulations across different regions.
Related Topics
Digital Marketing, SEO Specialist, Content Creator & Product Professional
Olayinka is a digital marketer, content creator, growth and SEO specialist with 10+ years helping businesses in Nigeria, the UK, the US, Australia, and Dubai achieve their goals online.